Contractors: Miller Act Bonds, $150,000 Threshold and 90 Day Notice
The Miller Act requires two bonds, a performance bond and a payment bond, on most federal construction contracts exceeding $150,000. The performance bond protects the government if you default; the payment bond protects the subcontractors and suppliers who never see a dime from the government directly and have no lien rights against federal property.
TL;DR:
- Prime contractors must provide both a performance bond and a payment bond on federal projects exceeding $150,000, with the bonds covering completion and payment protections for the government and subcontractors.
- Only first- and second-tier claimants can file Miller Act claims, with second-tier claimants required to send written notice within 90 days and file suit within one year of last work or supply.
- Bonds are typically required for projects over $150,000, while smaller projects under $35,000 usually do not need bonding, and alternative security may be used in the $35,000 to $150,000 range.
- Proper documentation, serving notices correctly, and following deadlines are crucial to avoid claim rejections, with venue limited to federal district courts where the work was performed.
- Surety bonds often deviate from standard forms and can expose owners and principals to personal liability under indemnity agreements, making early, thorough compliance essential.
Table of Contents
- What Miller Act Bonds Actually Require Under 40 U.S.C. § 3131
- Who Can File a Payment Bond Claim, and When
- How FAR Thresholds Determine When You Need a Full Bond
- A Compliance Checklist That Prevents Lost Claims
- Sureties, Bond Forms, and How Courts Read the Fine Print
- What I Tell Contractors Before They Bid Bonded Federal Work
- Get Help Navigating Federal Bonding and Compliance
- Sources
- FAQ
What Miller Act Bonds Actually Require Under 40 U.S.C. § 3131
The statute governing Miller Act bonds sets out two distinct obligations for prime contractors on covered federal construction work. Both bonds serve different parties, and confusing the two is one of the fastest ways to misread a solicitation.
- Performance bond: Guarantees the government that you will complete the contract as specified. The contracting officer sets the amount, and 100% of the contract price is common practice.
- Payment bond: Guarantees subcontractors and suppliers get paid for labor and materials. This bond usually equals the full contract price as well.
- Additional security: The contracting officer can require more security than the statute’s baseline if the project carries elevated risk.
- Foreign work waiver: The contracting officer may waive Miller Act bonding entirely for contracts performed outside the United States.
The Federal Acquisition Regulation implements this statute through FAR Part 28, and the government publishes standard forms, SF 25 for performance bonds and SF 25-A for payment bonds, for agencies to use. The Miller Act itself doesn’t strictly mandate these exact forms. Courts have generally upheld bonds that deviate from the standard language as long as they meet the statute’s substantive purpose.
Who Can File a Payment Bond Claim, and When
Not every unpaid party on a federal job gets to sue on the payment bond. The Miller Act draws a clear line based on privity, meaning your contractual relationship to the prime contractor, and missing a deadline can void an otherwise valid claim.
- First-tier claimants have a direct contract with the prime contractor and can sue on the payment bond without giving advance notice.
- Second-tier claimants work for a subcontractor rather than the prime, and they must send written notice to the prime within 90 days of last furnishing labor or materials. Certified mail with return receipt or delivery through a U.S. marshal are the methods courts most reliably recognize as proof of service.
- Suppliers to suppliers and other parties beyond the second tier generally fall outside Miller Act protection entirely, regardless of how much they contributed to the job.
- Pre-suit waiting period: Every claimant must wait 90 days after last furnishing labor or materials before filing suit, even after notice is served.
- Suit deadline: You must file suit within one year of the date you last performed work or supplied materials, not one year from the invoice date or the payment due date.
- Venue: Miller Act suits belong exclusively in federal district court for the district where the contract was performed. State court is not an option.
How FAR Thresholds Determine When You Need a Full Bond
The Miller Act sets the legal floor, but FAR Part 28 does the actual work of deciding what shows up in your solicitation. The dollar thresholds matter more than most contractors realize when they’re pricing a bid.
- Under $35,000: No bond is typically required at all.
- $35,000 to $150,000: The contracting officer selects an alternative payment protection instead of a full bond. Options include an irrevocable letter of credit, an escrow account, a certificate of deposit, or U.S. government bonds or notes.
- Above $150,000: Full performance and payment bonds are required under the FAR’s tiered structure, which raises the practical threshold well above the statute’s original baseline.
Even in the $35,000 to $150,000 range, plenty of solicitations still call for surety bonds by default. Agencies often find bonds administratively simpler than tracking escrow accounts or letters of credit, so don’t assume the middle tier means no bonding company gets involved.
A Compliance Checklist That Prevents Lost Claims
Most Miller Act claims fail on procedure, not merit. The work was done, the invoice is real, but the paperwork trail has a hole in it.
- Keep every invoice, delivery ticket, certified payroll record, change order, and lien waiver from day one of the project.
- Serve second-tier notices by certified mail or through a U.S. marshal, and keep the delivery receipt permanently.
- Watch for “pay-if-paid” clauses buried in subcontract language. They don’t override your Miller Act rights, but they complicate collection.
- Preserve pass-through claims in writing if a lower-tier sub is relying on you to pursue the prime or the surety.
- Review any General Indemnity Agreement carefully. Many require personal guarantees from owners, which survive even after the company dissolves.
When a contractor defaults, the surety typically steps in to complete the work or pays out claims up to the bond amount, and claimants should expect the surety’s own investigation process to take time before funds move.
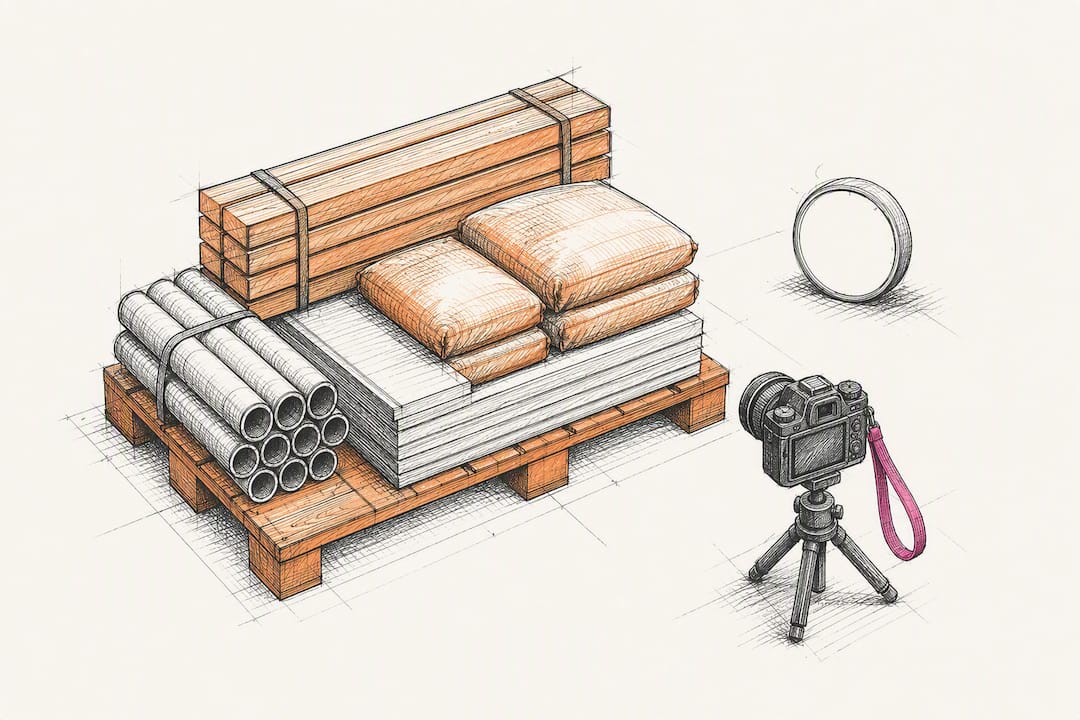
Pro Tip: Photograph and date-stamp material deliveries on-site. A timestamped photo has settled more than one notice-timing dispute where certified mail receipts got lost in a project file.
Sureties, Bond Forms, and How Courts Read the Fine Print
A surety isn’t a bank. It’s underwriting your ability to finish the job, and it prices that risk based on your financial statements, your backlog, and often your personal credit.
- SF 25 and SF 25-A remain the government’s preferred forms, but agencies and sureties do issue bonds with modified language, and courts generally accept them if the substance matches Miller Act requirements.
- A General Indemnity Agreement typically requires the business and its principals to indemnify the surety for any loss, which means a company owner’s personal assets can be exposed even when the business itself is properly capitalized.
- Courts tend to construe Miller Act protections broadly because federal property cannot be liened, so subcontractors have no fallback remedy without the bond.
- Sureties still raise real defenses, including pay-if-paid arguments and disputes over whether a claimant qualifies as first or second tier, so don’t assume the bond pays out automatically.
Building bonding capacity before you need it, meaning clean financial statements and a predictable backlog, does more to secure favorable bond terms than anything you can do after a solicitation lands in your inbox. A payment processing partner like Paysec can also help construction businesses keep the payment records sureties want to see.
What I Tell Contractors Before They Bid Bonded Federal Work
Three things matter more than anything else on a bonded job: confirm the exact bond amounts and forms named in the solicitation before you price the bid, build a notice calendar the day the contract is signed, and never let your records lag behind the work. I’ve seen more claims die from a missing delivery ticket than from a bad legal argument.
The mistake I see most often isn’t ignorance of the Miller Act. It’s contractors treating a General Indemnity Agreement as boilerplate when it’s the single document most likely to reach into their personal finances. Read it before you sign it, every time.
One more thing worth remembering: if your project is state or local rather than federal, look up your state’s Little Miller Act. The rules rhyme with the federal statute, but the deadlines and thresholds are rarely identical.
— Rowena
Get Help Navigating Federal Bonding and Compliance
Our service is designed to address common compliance gaps contractors encounter on bonded work, RFP writing, FAR and Davis-Bacon compliance, SAM.gov registration, and certified payroll support, helping you spend less time decoding solicitation language and more time running your jobs.
Handling bond compliance internally works fine when you have a dedicated estimator who already knows FAR Part 28 cold. Most small and mid-sized contractors don’t, and that’s when a missed notice deadline or a misread bond threshold turns into a lost claim or a rejected bid. We help ensure SF 25 paperwork, contract thresholds, and payment protections are correct before submission, not after a subcontractor calls asking why they haven’t been paid. If you’re bidding on bonded federal work and want a second set of eyes on your compliance package, start with the federal procurement services page to see what a compliance review covers.
Sources
For the primary legal text, consult 40 U.S.C. § 3131 and FAR Part 28 directly. For practice-level guidance on claim mechanics and deadlines, the American Bar Association’s construction industry publications and Smith Currie’s bonding primer both offer detailed breakdowns worth bookmarking.
- Acquisition
- 40 U.S. Code § 3131 - Bonds of contractors of public buildings or works
- Miller Act Payment Bond Claims: The Basics
FAQ
What Are the Four Types of Bonds in Construction?
The four common construction bond types are bid bonds, performance bonds, payment bonds, and maintenance bonds, with the Miller Act specifically requiring performance and payment bonds on covered federal contracts.
How Much Does a $30,000 Surety Bond Cost?
Bond premiums typically run a small percentage of the bond amount based on the contractor’s credit and financial strength, so the cost varies by surety underwriting.
Do I Have to Pay Back a Surety Bond?
Yes. If the surety pays out a claim on your behalf, it will pursue you and any guarantors under the indemnity agreement to recover that money, since a bond is a credit instrument, not free insurance.
What Are the Risks of Using an Indemnity Bond?
The main risk is personal exposure. Most General Indemnity Agreements require owners to personally guarantee repayment, which means your personal assets can be at stake even if your business stays solvent.
Who Can File a Claim Against a Miller Act Payment Bond?
First-tier subcontractors and suppliers with a direct contract to the prime can sue without prior notice, while second-tier claimants must send written notice within 90 days of last furnishing labor or materials.
Recommended
- Why Federal Contracts Require Bonding: A Contractor’s Guide
- Bid Bond in Public Estimating: A Contractor’s 2026 Guide
- Cure Notice in a Federal Contract: What Contractors Must Know
- Federal Contract Ceiling Limits Explained for Contractors
Working in the public sector? One short email a week — prevailing wage, certified payroll, bid protests, agency procurement rules. Free, no pitch. Subscribe.
Free and unconditional. No call required, no obligation, unsubscribe anytime.